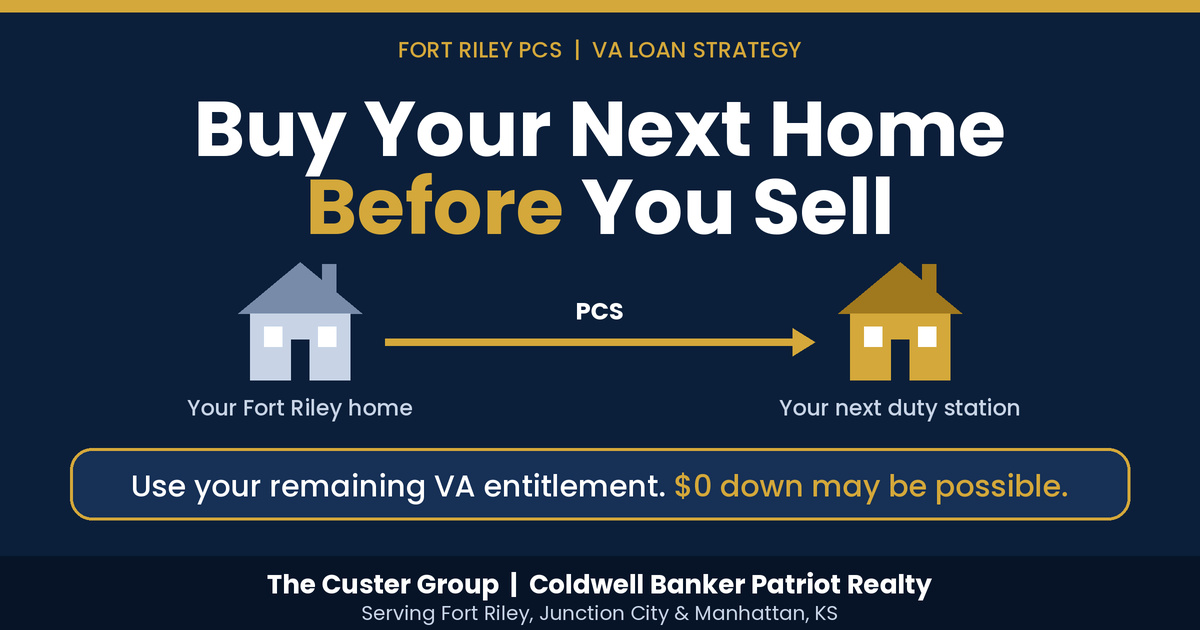
Yes — if you have remaining VA loan entitlement, you can leverage "second-tier" (bonus) entitlement to purchase a home at your next duty station with little to no money down before your current house sells.
How much you can borrow with $0 down hinges on your remaining entitlement and the 2026 conforming loan baseline limit of $832,750. Lenders will also evaluate whether you can qualify to carry both mortgage payments simultaneously. For most Fort Riley families PCSing with a home currently valued in the $220k–$380k range, there is typically plenty of entitlement left over to make this strategy work.
What Is Second-Tier VA Entitlement?
Every eligible service member and veteran holds a total VA loan entitlement tied to the Federal Housing Finance Agency (FHFA) conforming loan limit — set at $832,750 for 2026 in standard-cost counties. When you purchase a property using a VA loan (for example, a $280,000 home near Fort Riley), you commit a portion of your entitlement to that property.
Any entitlement you haven't used remains available as your second-tier (bonus) entitlement. The VA allows you to put this balance toward a second VA mortgage without having to sell or pay off the first house first.
This flexibility allows families PCSing out of Fort Riley to destinations like Fort Campbell, Fort Bragg, or Fort Bliss to purchase a home at their new station ahead of time, avoiding the stress of an artificially rushed sale in Kansas.
How Much Can You Borrow With Zero Down in 2026?
The standard entitlement calculation works as follows:
- Take the conforming loan limit for the county you are moving to ($832,750 in most standard-cost areas).
- Subtract the original loan balance or entitlement tied up in your current Fort Riley home.
- Multiply the remaining guarantee amount by 4.
If the purchase price of your incoming home is at or below that final threshold, you can purchase with $0 down. With the baseline conforming limit at $832,750, military homeowners selling a $220k–$380k property in the Flint Hills area often retain well over $400,000 in zero-down purchasing power at their next station.
If the price of the home you want exceeds your available bonus limit, you can simply bring a down payment equal to 25% of the difference, rather than waiting for your Kansas home to close.
Key Factors: Funding Fees and Debt-to-Income (DTI)
Two essential underwriting components will shape your approval:
- The VA Funding Fee
- First-time VA use: Carries a 2.15% fee when putting $0 down.
- Subsequent use: Rises to 3.3% with $0 down. However, putting down 5% drops that fee down to 1.5%.
On a $300,000 purchase, that difference ranges from roughly $9,900 (at 3.3%) to $4,500 (at 1.5%), so it pays to review both financing scenarios with your lender. (Note: Veterans receiving VA disability compensation are generally exempt from this fee.)
- Debt-to-Income (DTI) Ratios Underwriters will calculate your borrowing capacity based on carrying both mortgages at the same time, unless:
- Your Fort Riley home is already under an unconditional, binding sales contract, or
- You can supply a signed lease agreement demonstrating tenant income to offset the existing mortgage payment.
DTI capacity is the most common hurdle for PCS buyers attempting this move. Securing a formal pre-approval for the second mortgage should always be your first step.
What This Means for Fort Riley PCS Families
Current market dynamics in the Flint Hills region favor this transition:
- Fast Turnover: Well-priced properties near Fort Riley and Junction City are going under contract in approximately 16 days.
- Consistent Appreciation: Junction City's median home value continues an upward trajectory (up ~9.11% year-over-year).
Because local inventory moves briskly, a properly priced Fort Riley home rarely languishes on the market. Pairing robust local liquidity with bonus VA entitlement turns the "buy first, sell second" plan into a practical, low-stress PCS transition rather than a gamble.
Frequently Asked Questions
Do I have to notify the VA before using second-tier entitlement?
No separate authorization or pre-approval from the VA is required. Your mortgage lender pulls your Certificate of Eligibility (COE) directly through the portal to verify your remaining balance. You will simply need to keep your current loan servicer updated on your forwarding address and property status.
Will I qualify for two VA loans at once?
Yes, provided your income supports both obligations. Lenders will factor in both mortgage payments unless you have an executed purchase contract on your Kansas home or a signed lease with a tenant in place to offset the debt.
Does my remaining entitlement show up anywhere I can check myself?
Yes. Your Certificate of Eligibility (COE) outlines your entitlement status and any existing guaranty amounts. Any VA-approved mortgage specialist can pull and interpret your COE in a matter of minutes.
Is it better to sell my Fort Riley home first, then buy?
It depends on your finances and risk comfort. Buying first eliminates temporary housing, double-moving expenses, and the pressure of coordinating back-to-back closing dates. However, you must have the qualifying income and reserves to carry both payments comfortably if closing timelines overlap.
Ready to Map Out Your Buy-Before-You-Sell Strategy?
With over 25 years of experience guiding military service members through PCS relocations across Fort Riley, Junction City, Manhattan, and the surrounding Flint Hills communities, our team can help you navigate the process end-to-end. We'll help you calculate your available entitlement, coordinate with reputable VA lenders, and price your home to sell smoothly on your timeline.
Call or message us today to schedule your PCS consultation.
Check out this article next