VA Loan Rates Are Rising This Fall — What It Means for Fort Riley PCS Buyers
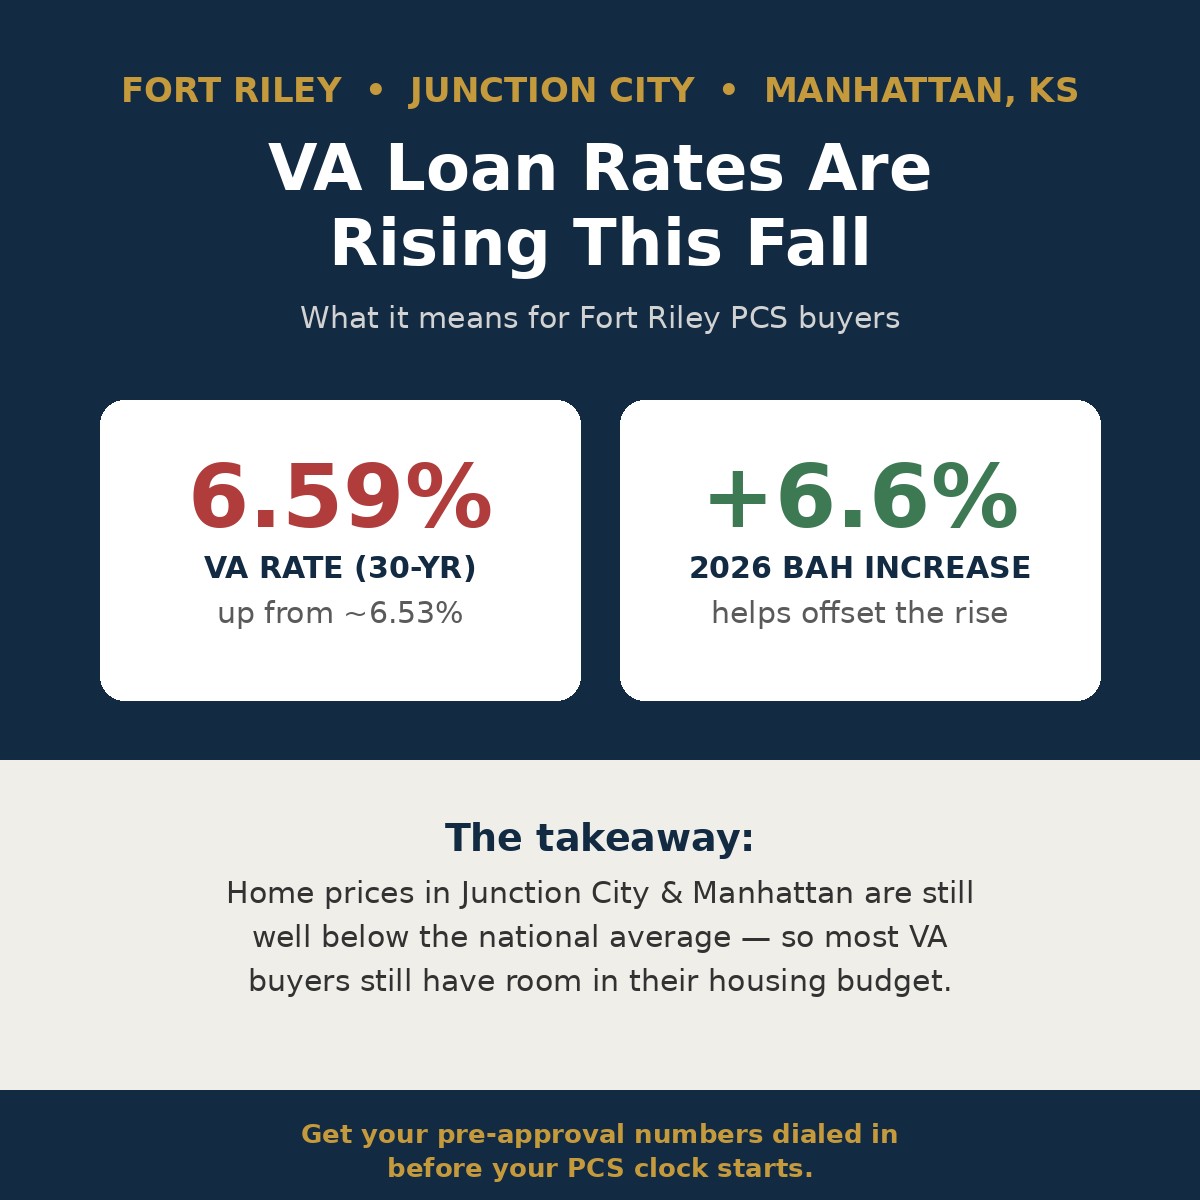
VA loan rates have climbed to roughly 6.59% for a 30-year fixed loan as of mid-September 2026, up from about 6.53% the week before, driven mainly by rising 10-year Treasury yields. For Fort Riley families PCSing this fall, that translates to a modestly higher monthly payment than earlier this year — but the 2026 BAH increase of about 6.6%, combined with home prices in Junction City and Manhattan that remain well below the national average, means most VA buyers still have real room in their housing budget.
What are today's VA loan rates for Fort Riley buyers?
As of mid-September 2026, 30-year fixed VA loan rates are running around 6.59%, up from about 6.5% the week before. VA loan rates track the 10-year Treasury yield more closely than almost any other mortgage product, and several rate-tracking services (Bankrate, CNBC/Optimal Blue, Veterans United) are all showing week-over-week increases through early and mid-September. This is a national trend, not anything specific to Fort Riley or Kansas, but it still changes the math for anyone PCSing here and shopping for a mortgage right now.
How much does a higher rate actually cost per month?
The impact is smaller than the headlines make it sound, but it's real. On a $300,000 VA loan, every quarter-point increase in the rate adds roughly $45–$50 to the monthly principal and interest payment. Move a full point, and that's closer to $180–$200 more per month. That's why locking in a rate as soon as a buyer is under contract, rather than floating and hoping for a dip, is usually the safer play once there's an accepted offer in hand.
Will rising rates hurt affordability in Junction City and Manhattan, KS?
Less than in most markets. 2026 BAH rates rose about 6.6% year-over-year, and this area's home prices are still some of the most affordable near any major Army post. Junction City home prices average well under $150,000, and Manhattan, while pricier and more sought-after for its schools and K-State-area amenities, is still far below national medians. Even with rates near 6.6%, most E-5 to O-4 households can comfortably cover principal, interest, taxes, and insurance within their housing allowance in both markets.
Should a buyer lock their VA loan rate now or wait to see if rates drop?
If a buyer already has orders and a home search underway, don't try to time the market. Get pre-approved at today's rate so the search targets homes that fit current conditions, and lock the rate as soon as the home is under contract. If a buyer is still months out from PCS orders, it's worth asking the lender about a float-down option, which allows locking now while still capturing a lower rate if one becomes available before closing.
Does a higher rate change how much home a buyer can afford with their BAH?
Yes. Getting pre-approved using today's rate, not an outdated one, ensures the home search targets a price point that the current market and the buyer's allowance can actually support.
With 25+ years of experience helping military families buy and sell around Fort Riley, Geary County, and the Flint Hills, we can run your numbers against today's actual rates and BAH so you know exactly what you can afford before you start touring homes. Call or text us and let's get your pre-approval numbers dialed in before your PCS clock starts.
Check out this article next